FHA Appraisal and Repair Pitfalls in Tampa: What Buyers Should Watch for Before Closing
By Ryan Kearns, NMLS 1826973
FHA appraisals in the Tampa Bay area can be tricky, especially with the heat, humidity, and older homes. Eligibility depends on borrower profile, property type, and program guidelines. Many buyers are surprised when an appraiser calls out repairs right before closing, and everything has to pause while contractors come in and the clock keeps ticking. You can avoid a lot of stress if you know what FHA appraisers look for and how Tampa's climate affects a home.
This article will walk you through how FHA appraisals really work, the most common repair problems in local homes, and what you can check early so you are not scrambling at the last minute. When you understand this ahead of time, you can plan your timing, funds needed at closing, and negotiation strategy before you get attached to a house that may need work.
How FHA Appraisals Really Work in Tampa
An FHA appraisal has two main jobs. First, it checks that the value of the home supports the loan. Second, it looks at basic safety, soundness, and security underHUD Minimum Property Requirements. That means the appraiser is not doing a full home inspection, but they are watching for obvious hazards and conditions that might affect whether FHA financing is allowed. Homebuyers should always obtain an independent, comprehensive home inspection, as an appraisal is designed to protect the lender's security interest rather than identify every potential defect.
Here is what usually happens in a Tampa FHA purchase under theFHA loan options program:
- Your lender orders the appraisal after you go under contract
- The appraiser schedules a visit to the property
- They send a report to the lender with value and any needed repairs
- If repairs are required, those items must usually be fixed and re-inspected before closing
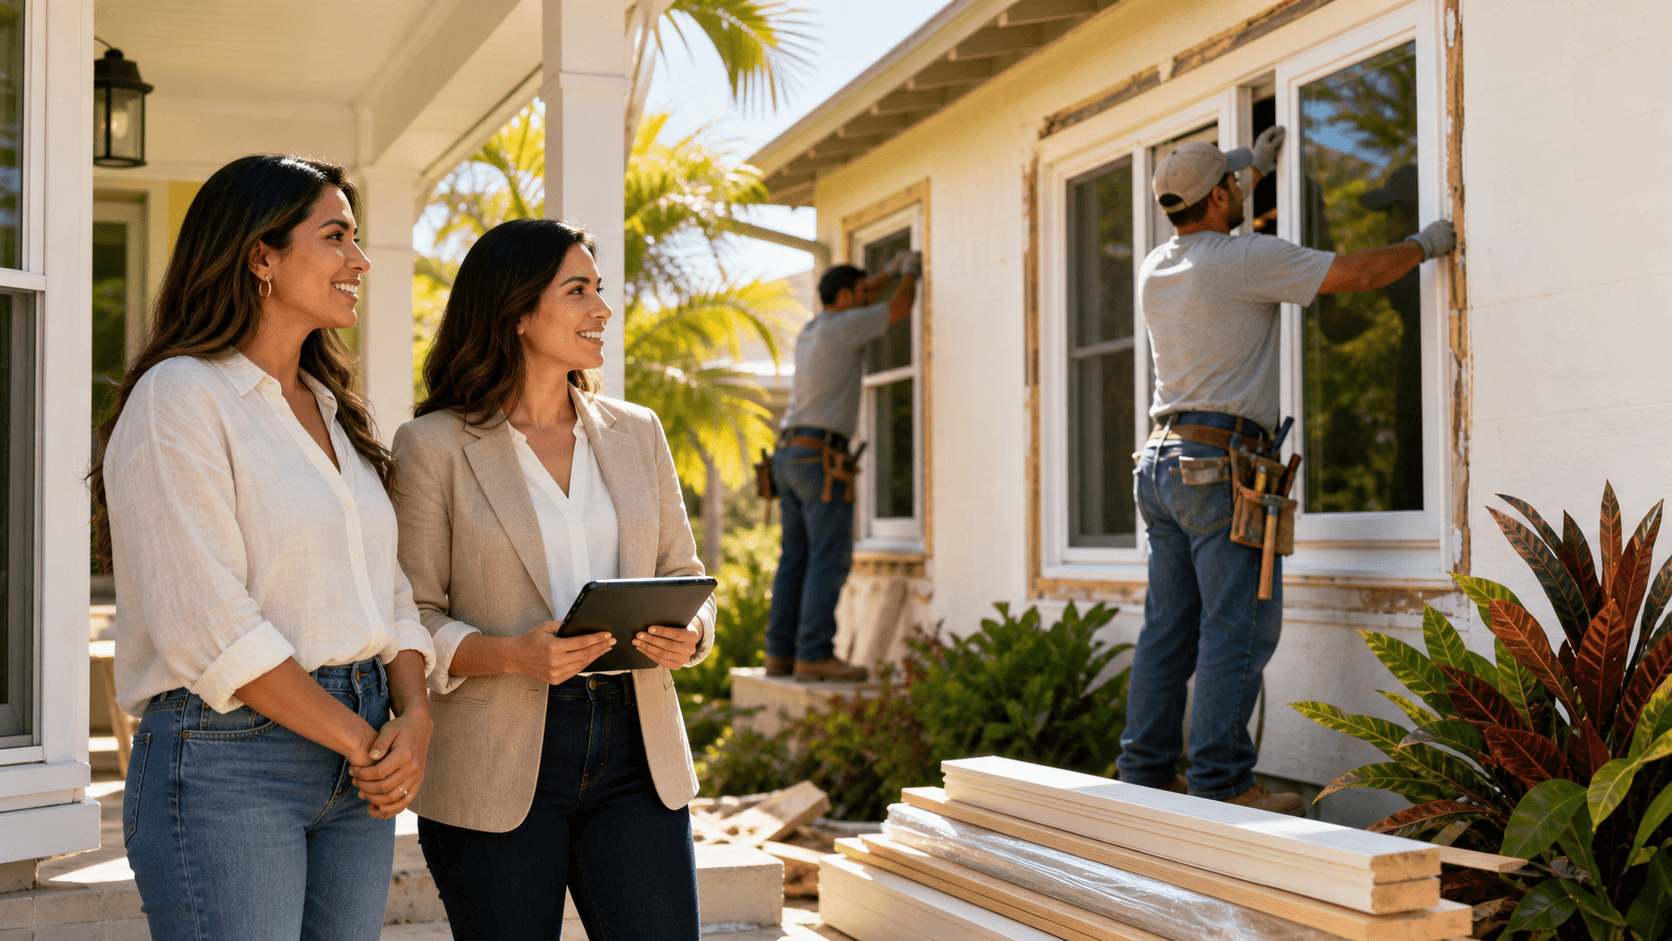
During busy times or storm season, it can be harder to get quick appointments. Roofers, AC techs, and electricians may be booked out, and heavy rain can slow down outside repairs or re-inspections. If the appraiser has to go back out to confirm repairs, that can add extra days to your timeline.
When an appraiser calls out a repair, your loan may be on hold until the work is done. That can affect:
- Your closing date
- How long your rate lock needs to last
- How you and the seller split repair costs or credits
This is where planning and communication with your Realtor and lender really matter.
Common FHA Repair Flags in Tampa Homes
Some issues pop up again and again in Tampa FHA appraisals, especially with older homes and homes that have not been kept up in the humid climate. FHA guidelines focus on active hazards and structural issues rather than cosmetic wear or age alone.
Common structure and moisture problems:
- Roofs at the end of their life or with active leaks
- Damaged or rotted soffits and fascia from moisture or pests
- Poor drainage that sends water toward the slab or foundation
- Gutters or downspouts missing where they are clearly needed
Safety items FHA appraisers often note:
- Missing or loose handrails that pose a safety hazard
- Broken or cracked windows that pose a safety hazard
- Peeling or chipping paint on homes built before 1978 (due to lead-based paint rules) or where bare wood is exposed to weather and rot
- Missing smoke alarms or carbon monoxide detectors where required by local building codes
Minor cosmetic defects, harmless cracked glass and small plumbing leaks that cause no damage may not require repairs. Age alone does not require replacement of a functioning component with remaining useful life.
Systems that can raise questions in the heat and humidity:
- Air conditioning systems that fail to operate or cool properly (age alone does not trigger a repair, but functional failure does)
- Unsafe, inadequate or damaged electrical panels
- Older plumbing with visible leaks or corrosion
None of these automatically ruin a deal, but they may trigger required repairs before your FHA loan can move forward.
What Buyers Should Check Before the Appraisal
You do not need to be an expert to spot early warning signs. During showings and your home inspection, pay attention to things that might catch an appraiser's eye.
Simple things to look for as you walk through:
- Brown rings or water stains on ceilings or walls
- Soft spots in flooring, especially near bathrooms and kitchens
- Wood that looks chewed, hollow, or crumbly, which might hint at termites
- Obvious cracks, missing siding, or heavy wear on the exterior
- Loose railings or steps that wobble
Ask your Realtor and inspector clear questions about:
- Roof age, recent repairs, and any past leaks
- AC age, service history, and how well it cools the home
- Electrical panel type and any known issues
- Past insurance claims for water damage, wind, or fire
Also, take time to review seller disclosures and any repair invoices they share. If you see recent roof work, AC replacement, or plumbing fixes, that can be helpful context for what an FHA appraiser may see.
Working With an FHA Mortgage Broker in Tampa
An FHA mortgage broker in Tampa can help you match the property to the right loan type. If a home needs repairs, it may change how you structure things like seller credits and how much you want to keep in reserve for your funds needed at closing. Note that while seller credits can help offset buyer closing costs, a credit or price reduction cannot replace a required physical repair; the work must actually be completed prior to closing unless the lender establishes an FHA-permitted repair escrow; the home must still be habitable and safe to occupy at closing.
A local broker can:
- Look at your home inspection and point out items that may matter to FHA
- Coordinate with your Realtor when the appraiser asks for repairs
- Help you understand how lender credits or seller credits could shift if more repairs pop up
If timing gets tight, your broker can also explain how appraisal delays might affect your rate lock and your final "cash to close," which is the total amount you bring to closing after credits and deposits.
If you decide to compare other loan types alongside FHA, it can also help to look at options like aconventional home loan or even aVA home loan if you qualify for that program.
Summer Timing Tips and FHA Appraisal FAQs for Tampa Homebuyers
Late summer in Tampa can be busy for both real estate and contractors. Heavy afternoon storms and hurricane season can slow roof work, exterior painting, and any repair that needs dry weather.
A few timing tips for FHA buyers here:
- Build some extra days into your contract where you can
- Order the appraisal as soon as your lender allows
- Tackle safety and roof items first, since those are common FHA issues
- Stay flexible if your appraiser needs a re-inspection after repairs
Below are some quick FHA appraisal FAQs for Tampa buyers.
Are FHA Appraisals Stricter Than Conventional Appraisals?
Both consider value and property condition. FHA applies HUD property requirements. Conventional loans also have property standards; for example, Fannie Mae requires repairs for defects affecting safety, soundness or structural integrity. The specific property and loan requirements matter.
Who Usually Pays for FHA-Required Repairs in Tampa?
It is negotiable between buyer and seller who covers the cost of physical repairs. However, offering a seller credit or price drop does not clear a required repair condition; the physical work must be finished and re-inspected before closing unless the lender establishes an FHA-permitted repair escrow; the home must still be habitable and safe to occupy at closing.
How Long Do FHA Repairs and Re-Inspections Usually Take?
It depends on the type of work and contractor schedules. Simple fixes can be quick, but bigger jobs like roof repairs or wood replacement can take longer, especially when many homes need work at the same time.
Can an FHA Appraisal End My Deal If Major Issues Show Up?
Serious structural, roof, or safety problems can make FHA financing difficult if they are not fixed. In that case, you, your Realtor, and your FHA mortgage broker in Tampa can talk through options, like asking the seller for repairs or deciding if the home still fits your goals.
Will I Get a Copy of the FHA Appraisal Report?
Yes. Under Regulation B and federal law, your lender is required to provide you with a free copy of all completed written appraisals and valuations promptly upon completion, or no later than three business days before closing, whichever is earlier, even if the loan does not close. A valid waiver can change the delivery timing, but not your right to the copies. (While the copy itself is provided at no charge, you may still be responsible for the cost of the appraisal fee.) See theCFPB Appraisal Rule guidance for additional details.
Call or text our office line at 813-796-5755 to discuss FHA appraisal requirements and financing options.
Kearns Mortgage Team, LLC, NMLS 2177472. Ryan Kearns, NMLS 1826973. All loans are subject to credit approval. This is not a commitment to lend. Terms and conditions may apply and are subject to change without notice. Programs, rates, and eligibility subject to underwriting approval and availability. Equal Housing Opportunity.